
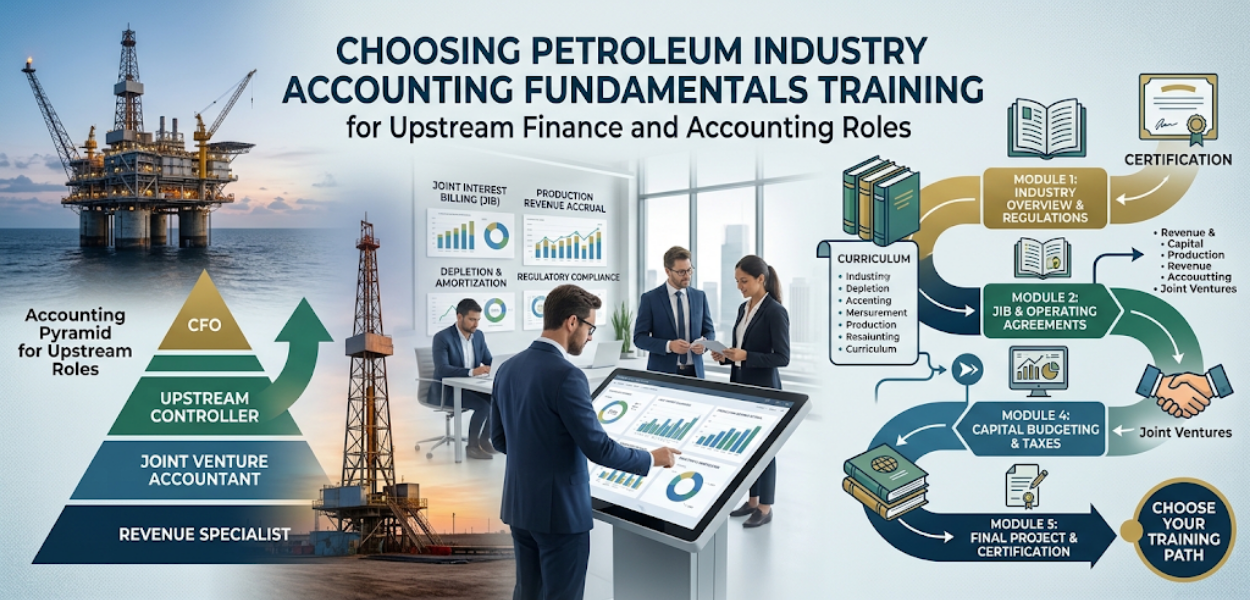
What does Oil & Gas Petroleum Accounting training solve for upstream finance teams?
Oil & Gas Petroleum Accounting training develops the practical accounting knowledge required to classify, capitalise, expense, allocate, depreciate, deplete and assess upstream petroleum costs accurately across exploration, development and production activities.
Upstream finance and accounting roles require more than general accounting knowledge. Professionals must understand how petroleum operations affect financial records, asset values, cost centres, cash flow and performance reporting. A classification decision made during exploration can influence later capitalisation, depletion, impairment assessment and reported field economics.
The course is designed around these industry-specific requirements. It connects accounting principles with upstream activities so participants can interpret cost movements within the petroleum lifecycle and understand why particular accounting treatments are applied.
The starting point is the knowledge gap addressed in the awareness-stage article understanding why upstream cost classification matters for field performance. This establishes the operational context before participants move into detailed accounting treatment.
At Institute For Oil & Gas Training, the Oil & Gas Petroleum Accounting programme can therefore be positioned as a structured professional development route for finance professionals, accountants, asset teams and managers who need petroleum-specific accounting competence.
Why is the course structured around upstream accounting decisions?
The curriculum follows the petroleum lifecycle because accounting decisions change as assets move from exploration through development and production, requiring participants to connect cost classification with capitalisation, expense recognition, allocation, depreciation, depletion and asset evaluation.
The curriculum progresses from fundamental accounting terminology towards specialised upstream applications. This prevents participants from learning individual accounting treatments without understanding the operational circumstances that create them.
The first stage establishes the relationship between petroleum operations and financial accounting. Participants examine revenues, costs, assets, liabilities, capital expenditure and operating expenditure within an upstream environment.
The next stage addresses capitalisation policy. Participants learn how accounting teams determine whether expenditure should be recognised as an asset or charged to the current period. This distinction is central to upstream reporting because exploration and development expenditure can produce different accounting consequences.
The curriculum then moves into expensed exploration costs, unproved property and dry hole accounting. These areas require participants to distinguish between expenditure associated with potentially recoverable resources and costs that do not meet the relevant criteria for continued recognition.
A later stage focuses on cost centre pooling and allocation. Participants learn how costs can be accumulated and assigned to appropriate assets, fields or activities. This supports consistent internal reporting and helps finance teams understand how cost allocation affects field-level performance analysis.
The final accounting stages address depletion, depreciation and amortisation, asset evaluation, the ceiling test and the impairment of oil and gas assets. The progression creates a connected learning pathway rather than a collection of isolated accounting topics.
What will participants learn about petroleum accounting fundamentals?
Participants learn to interpret upstream accounting terminology, classify petroleum expenditure, apply capitalisation and expense principles, understand cost pooling, analyse asset movements and connect accounting treatment with operational and financial reporting requirements.
The foundation module develops the terminology needed to work effectively with petroleum finance teams. Participants examine the accounting concepts that underpin upstream transactions and financial reporting.
The cost classification module then develops practical judgement around expenditure. Participants work through distinctions between capital and operating costs and consider how the classification of an expenditure item can affect asset recognition and reported results.
The capitalisation policy module focuses on the rules and decision processes used to determine which costs remain associated with an asset. Participants learn to assess expenditure according to its accounting treatment rather than simply its operational description.
The exploration accounting module covers expensed exploration costs, unproved property and dry hole accounting. These topics are particularly relevant to teams dealing with exploration portfolios where unsuccessful activities and uncertain resource outcomes must be reflected appropriately.
The cost allocation module introduces cost centre pooling. Participants examine how expenditure can be grouped and allocated for reporting and management purposes. Practical exercises can be used to show how inconsistent allocation approaches can distort comparisons between assets or activities.
The asset accounting module covers depletion, depreciation and amortisation. Participants learn how capitalised petroleum assets are subsequently reflected through systematic expense recognition.
The asset evaluation module addresses the ceiling test and the impairment of oil and gas assets. Participants develop the ability to interpret asset values in relation to relevant accounting assessments and understand the implications for financial reporting.
How does the curriculum build skills from basic concepts to workplace application?
Skill progression moves from terminology and classification into applied cost treatment, asset accounting and evaluation, allowing participants to develop accounting judgement progressively instead of attempting advanced petroleum accounting decisions without the necessary foundation.
The first learning level establishes terminology and basic accounting relationships. This is suitable for professionals who understand general finance but have limited exposure to petroleum accounting.
The second level introduces upstream cost decisions. Participants classify exploration, development and production expenditure and examine the consequences of different treatments.
The third level applies these principles to workplace scenarios. Participants consider how accounting teams process costs through cost centres, asset records and reporting structures.
The fourth level develops asset accounting capability. Depletion, depreciation and amortisation are considered in the context of petroleum assets rather than generic accounting examples.
The final level focuses on evaluation and reporting. Participants analyse the relationship between capitalised costs, asset values and impairment or ceiling-test considerations.
This progression is particularly relevant for organisations building finance capability across different career stages. HR teams can use the curriculum to identify appropriate participants for finance development programmes, while managers can align the training with role requirements.
At Institute For Oil & Gas Training, the structure can also support departmental learning because participants can enter with different levels of accounting experience while working towards defined petroleum-specific competencies.
How are practical petroleum accounting skills assessed?
Assessment should test whether participants can apply accounting principles to realistic upstream scenarios, with exercises covering classification, capitalisation, cost allocation, asset accounting and evaluation rather than relying solely on theoretical knowledge.
Practical assessment can begin with short knowledge tests covering petroleum accounting terminology and core concepts. These tests establish whether participants understand the principles required for later application.
Assignments can then require participants to classify selected upstream costs and explain the accounting treatment. The emphasis is on the reasoning behind each decision.
Scenario-based exercises can simulate exploration and production accounting situations. Participants may be required to distinguish capital expenditure from expenses, determine appropriate treatment for unsuccessful exploration activity and analyse the implications of different cost classifications.
Cost allocation exercises can assess whether participants can apply cost centre pooling principles consistently. These activities help connect accounting records with operational structures.
Asset accounting simulations can then introduce depreciation, depletion and amortisation calculations. Participants can interpret the resulting accounting impact rather than simply producing numerical answers.
At Institute For Oil & Gas Training, assessment can be incorporated into workshops, online learning activities, hybrid sessions or onsite corporate programmes, depending on the selected delivery arrangement.
How is Oil & Gas Petroleum Accounting delivered for corporate learners?
The programme can be delivered through instructor-led workshops, online sessions, hybrid learning or onsite corporate training, with the format selected according to participant roles, departmental requirements, geographic needs and organisational learning objectives.
Workshop delivery allows participants to work through accounting scenarios with an instructor and discuss the operational context behind each accounting decision.
Online delivery provides a structured option for geographically distributed finance teams. Participants can complete guided learning activities and applied exercises without requiring all team members to be physically present.
Hybrid delivery combines structured online learning with facilitated sessions. This can be useful where organisations require consistent foundational knowledge alongside interactive application.
Onsite delivery allows Institute For Oil & Gas Training to structure examples around departmental responsibilities and organisational workflows. Finance departments, asset teams and managers can participate within the same learning programme while examining different aspects of petroleum accounting.
The delivery format should be selected according to the required depth, participant availability, operational environment and assessment requirements. The core objective remains consistent: participants should demonstrate applied competence in petroleum accounting decisions.
How should organisations compare this course with other petroleum accounting learning options?
Course selection should be based on curriculum coverage, practical application, assessment depth, delivery format, participant eligibility and relevance to upstream accounting responsibilities rather than course title alone or generic finance training claims.
A general accounting course may provide useful financial knowledge but may not address exploration expenditure, unproved property, dry hole accounting, petroleum asset depletion or ceiling-test considerations.
A technical petroleum course may explain exploration, development and production activities without providing sufficient accounting treatment. For finance professionals, that creates a gap between understanding the asset and reporting its financial consequences.
The Oil & Gas Petroleum Accounting programme should therefore be evaluated against the specific competency requirements of the role. The decision criteria should include whether participants will study cost classification, capitalisation policy, exploration accounting, cost allocation, depreciation, depletion, amortisation and asset evaluation.
The evaluation stage can be supported by comparing how upstream costs are capitalised, expensed and allocated across the petroleum lifecycle. This provides the conceptual bridge between general cost classification and the structured learning delivered through the course.
Institute For Oil & Gas Training can use these criteria when aligning programme content with organisational capability frameworks. HR and L&D teams can also map modules against job descriptions and competency requirements before selecting participants.
What workplace outcomes can participants demonstrate after training?
Successful participants should be able to interpret petroleum accounting terminology, classify upstream costs, apply capitalisation and expense principles, analyse cost allocations and understand how depreciation, depletion, amortisation and asset evaluation affect reporting.
For finance professionals, the immediate outcome is stronger interpretation of upstream accounting transactions. Participants can communicate more clearly with exploration, production, asset and commercial teams because they understand the operational context behind financial entries.
For accounting teams, the training supports more consistent treatment of upstream expenditure. Participants can apply defined principles when reviewing costs and preparing internal accounting information.
For asset teams, petroleum accounting knowledge improves understanding of how operational decisions can affect financial reporting. This is particularly relevant when reviewing capital expenditure, exploration outcomes or asset performance.
For managers, the programme provides a framework for interpreting accounting information generated from petroleum activities. Managers can use this knowledge when reviewing departmental performance and financial implications.
For HR and L&D teams, measurable outcomes can be incorporated into development plans. Participants can be assessed against defined competencies before and after training, creating a clearer connection between learning activity and workplace capability.
At Institute For Oil & Gas Training, these outcomes fit within corporate skill development because the course connects technical accounting knowledge with practical workplace performance rather than treating accounting as an isolated academic subject.
Who should enrol in Oil & Gas Petroleum Accounting training?
The course is suitable for finance and accounting professionals, petroleum accountants, financial analysts, asset team members, managers and other professionals who require structured knowledge of accounting practices within upstream oil and gas operations.
The programme can support accountants moving into petroleum-sector roles who need to understand industry-specific accounting terminology and transactions.
It is also relevant to finance professionals already working in oil and gas who need to strengthen their understanding of exploration and production accounting.
Financial analysts can benefit from understanding how cost classification and asset accounting affect financial information. Asset team members can use the programme to improve communication with finance and accounting departments.
Managers who oversee budgets, projects or asset performance can also participate where petroleum accounting knowledge forms part of their decision-making responsibilities.
HR teams can consider the course when building development pathways for finance departments, particularly where employees are transitioning into upstream roles.
Participants do not need to approach the programme solely from an accounting perspective. Its value within corporate learning comes from connecting accounting treatment with petroleum operations and organisational reporting.
What should organisations consider before enrolling a team?
Before enrolment, organisations should identify the participants’ current accounting knowledge, upstream responsibilities, required competencies, preferred delivery method, assessment expectations and workplace applications so the programme matches measurable development requirements.
The first consideration is role relevance. Organisations should identify whether participants work directly with exploration, development, production, asset accounting, financial reporting or management information.
The second is existing knowledge. Experienced accountants may require deeper application exercises, while professionals new to petroleum accounting may need greater emphasis on terminology and fundamentals.
The third consideration is delivery. HR and L&D teams should determine whether workshop, online, hybrid or onsite delivery best fits operational schedules and participant locations.
The fourth is assessment. Organisations should define whether they require knowledge tests, practical assignments, case-based exercises or a combination of methods.
The fifth is workplace application. Managers can identify current accounting processes where participants will apply the learning, such as cost classification reviews, cost allocation analysis or asset accounting activities.
Institute For Oil & Gas Training can position these requirements within the programme structure so that learning objectives remain connected to professional responsibilities.
How does enrolment and completion work?
Enrolment should begin by confirming participant suitability, learning requirements and preferred delivery format, followed by programme participation, applied learning activities and assessment against the defined petroleum accounting competencies.
The first step is identifying the employees or professionals who require petroleum accounting development. Their current responsibilities and experience should be reviewed against the course scope.
The organisation can then confirm the required delivery method and learning objectives. For corporate groups, HR or L&D teams can coordinate participant numbers, scheduling and departmental requirements.
During the programme, participants progress through the curriculum from fundamentals to applied upstream accounting. Learning activities should provide opportunities to test classification decisions, examine accounting treatments and apply asset accounting principles.
Completion should be linked to demonstrated learning rather than attendance alone. Tests, assignments, simulations and practical exercises can provide evidence that participants understand the required concepts.
Institute For Oil & Gas Training provides the professional training context for this learning pathway, with the programme structured around workplace competence in petroleum accounting.
The final decision should therefore consider whether the curriculum, delivery model, assessment approach and participant profile match the organisation's upstream finance and accounting requirements. Professionals and corporate teams seeking structured development in Petroleum Industry Accounting Fundamentals can use these criteria to determine programme suitability and enrol in this programme.
Related training courses
Upstream Cost Classification for Recoverability & JV Chargeability Training Course
- Specialisation
- Oil & Gas Petroleum Accounting
- Duration
- 5 days · 15 CPD hours
Inventory & Materials Accounting: Drilling Consumables & Stock Training Course
- Specialisation
- Oil & Gas Petroleum Accounting
- Duration
- 5 days · 15 CPD hours
Inventory & Materials Accounting for Hydrocarbon Stock Valuation Training Course
- Specialisation
- Oil & Gas Petroleum Accounting
- Duration
- 5 days · 15 CPD hours
More articles
Oilfield Economics & Project Evaluation: Specialist Training for Petroleum Economics and Commercial Roles
Master petroleum economics and project evaluation with specialized training. Learn cash flow modeling, risk analysis, and fiscal contracts for upstream roles.
Read article →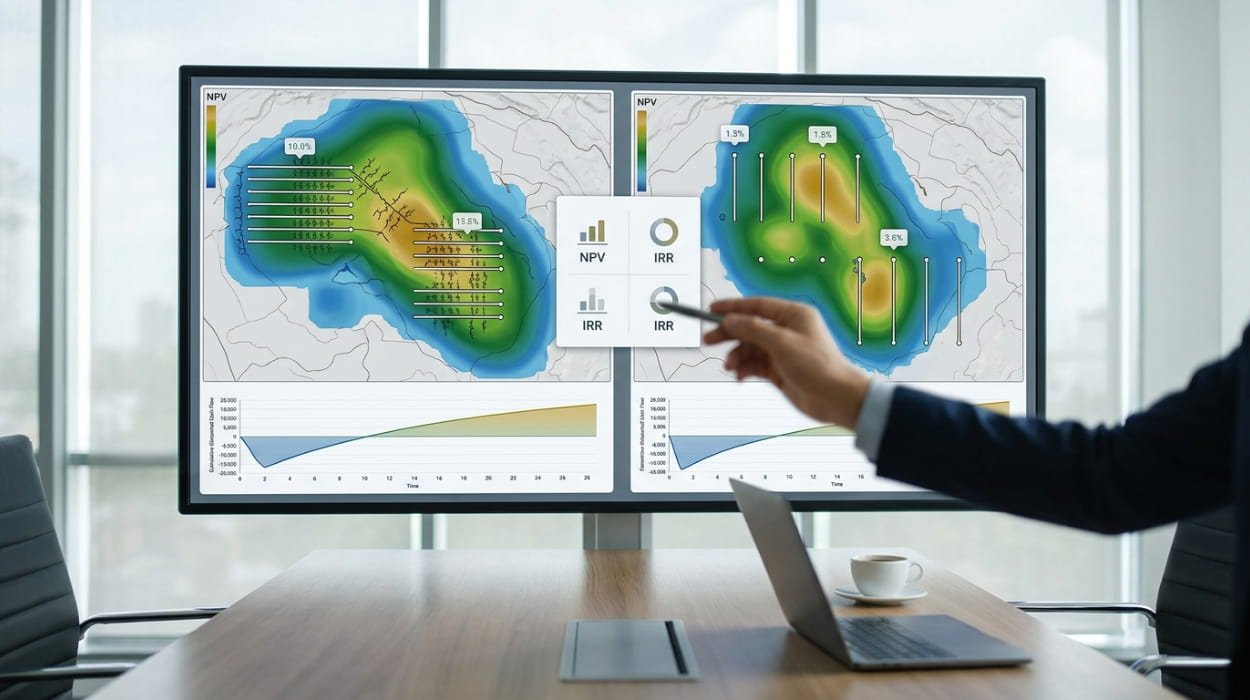
NPV and IRR Analysis for Comparing Alternative Oilfield Development Cases
Master net present value and internal rate of return methods to compare alternative oilfield development cases and optimize upstream capital allocation.
Read article →
How Petroleum Companies Assess the Commercial Viability of New Field Developments
Discover how petroleum companies train teams to assess field development commercial viability, optimize capital allocation, and drive project returns.
Read article →